How to Calculate Total Cost of Ownership for Looms
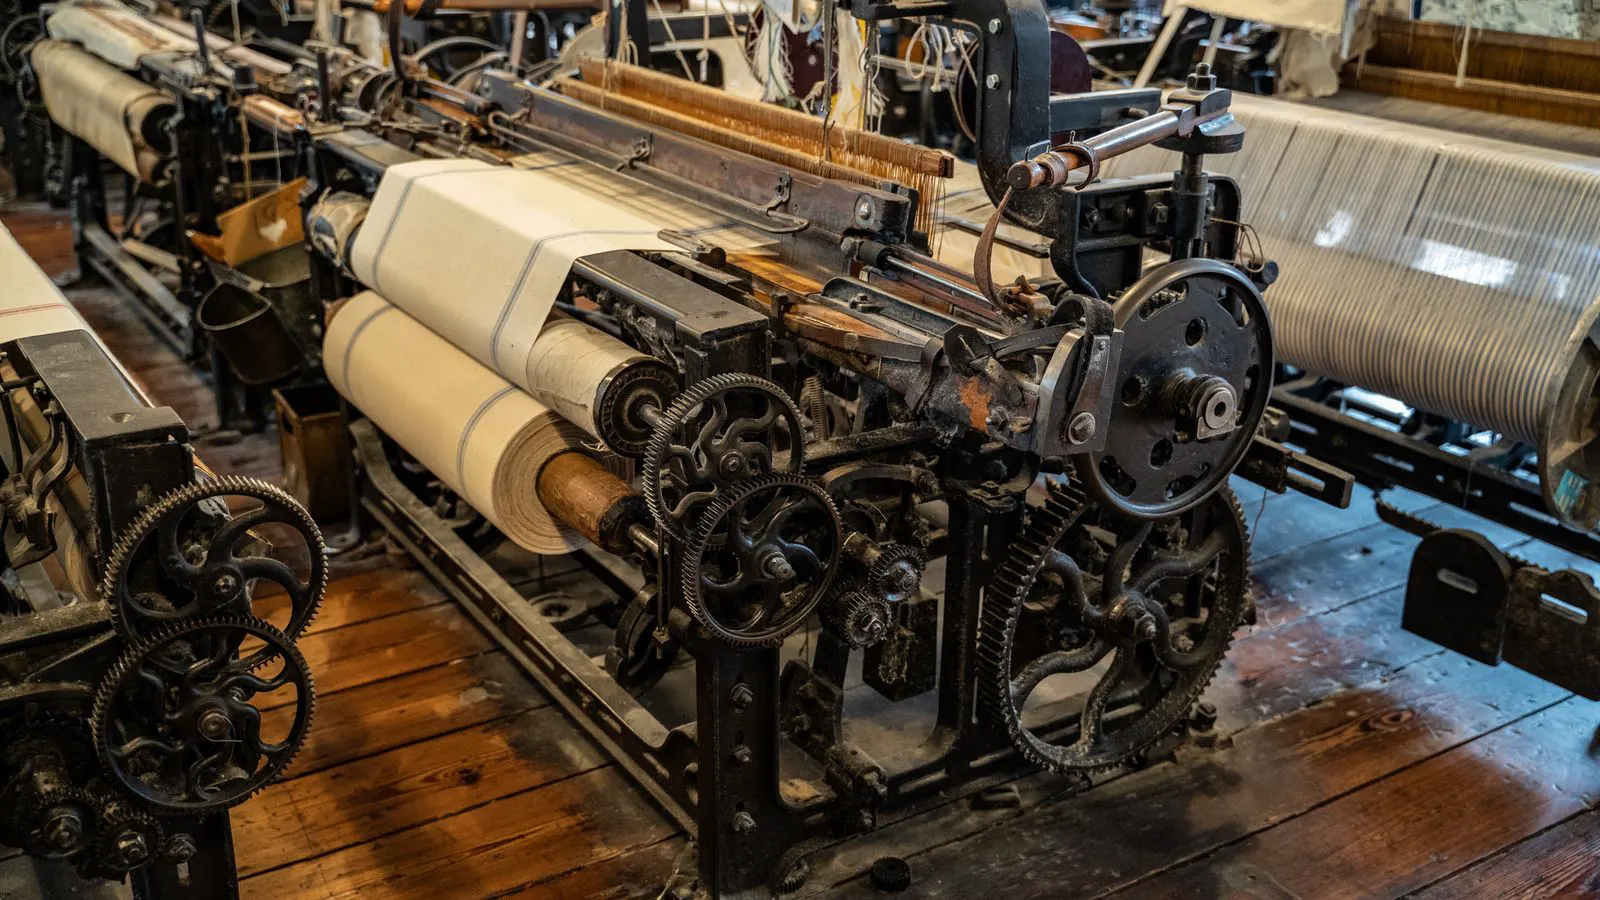
A loom TCO calculation sums the initial purchase price with operating, maintenance, and disposal costs over the machine's expected service life. This approach reveals the true financial impact of a weaving machine, helping buyers compare options against simple sticker prices.
- Loom TCO calculation includes purchase, installation, energy, maintenance, and labor costs over the machine's lifecycle.
- Energy and maintenance often exceed the initial purchase price over a decade of operation.
- Include downtime costs and spare parts inventory in the final sum.
- Use a consistent time horizon and discount rate for fair comparisons between loom options.
- Verify the final figure by reversing the calculation and checking each cost line.
Why the Purchase Price Is Not the Full Cost
The invoice from the loom supplier covers only the machine. A complete loom TCO calculation adds every expense that follows the purchase. Buyers who compare looms using sticker prices alone miss the real financial picture. A cheaper loom may carry higher energy use, more frequent breakdowns, and a shorter useful life. A pricier machine may deliver lower lifetime costs through better efficiency and longer service intervals.
This guide walks through the calculation in a sequence that mirrors how a plant finance team would build the model. It assumes you have access to supplier quotations, utility tariffs, and internal maintenance records. If you are evaluating a single new machine, the same method applies. If you are replacing a line, the method works for the whole line.
Before You Start: What You Need
Gather these inputs before opening a spreadsheet.
- Purchase price and any mandatory accessories from the supplier.
- Installation, foundation, and commissioning costs.
- Your local electricity tariff per kilowatt-hour.
- Estimated annual running hours and production cycle data.
- Planned maintenance intervals and spare parts prices.
- Labor rates for machine operators and maintenance technicians.
- Expected useful life of the machine in years.
- Discount rate or interest rate to apply for time value of money.
Without these, the loom TCO calculation stays in the abstract. A rough estimate is better than no estimate, but specific inputs produce defensible numbers. If a value is missing, use a conservative range and mark it as an assumption in your model.
Step 1: Establish the Purchase and Installation Cost
Start with the machine price. Add any items the supplier sells separately but that are required for operation. Common extras include a dedicated power cabinet, a control interface, a floor anchoring kit, and a compressed air preparation unit. Some suppliers bundle these; others list them as options.
Installation costs cover civil work, electrical connection, and the first commissioning run. If your plant already has a standard loom bay, this can be modest. If you need to reinforce a floor slab or run new conduit, the figure rises quickly. Record each line item separately so you can update it later if the scope changes.
The reason for this step is that the first year of ownership is often the most expensive. Installation errors or missing accessories create rework that adds cost and delays production. Capturing these upfront prevents surprise charges from inflating the TCO later.
Step 2: Model Energy Consumption
Energy is usually the largest recurring cost for a weaving machine. Multiply the machine’s power rating at full load by the number of hours it runs per year. Then apply your utility tariff. Do not use the nameplate power as if it is the average draw. Looms do not run at full load every cycle. The shuttle or pick mechanism draws a peak current, but the average draw over a production shift is lower.
Ask the supplier for the average power consumption at your target fabric width and speed. If they only give peak watts, request a duty cycle estimate. A typical power loom may draw a fraction of its peak during the main weaving cycle. If you cannot get this data, use the peak value as a ceiling and note that your final energy cost is an upper bound.
The reason for this step is that energy costs accumulate every day the machine runs. A small difference in efficiency compounds over thousands of hours. Two looms that look similar in purchase price can diverge by a meaningful margin in energy spend over ten years.
Step 3: Estimate Maintenance and Spare Parts
Maintenance is where loom TCO calculation gets granular. Split it into scheduled maintenance and unscheduled repair. Scheduled maintenance includes oil changes, belt adjustments, tension checks, and lubrication of moving parts. Unscheduled repair covers broken parts, worn shuttles, damaged warps, and control faults.
List the top ten parts that fail most often on your specific loom type. For each part, record the purchase price, the expected service interval, and the labor time required for replacement. Multiply the part price by the number of replacements per year. Add the labor cost at your local rate. Do this for each part, then sum the column.
The reason for this step is that maintenance costs vary widely by machine design and operating discipline. A loom that runs at high speed with aggressive yarn tension wears parts faster. A loom that sits idle for months develops corrosion and needs more intensive startup checks. Your internal service records are the best source for realistic failure rates.
Step 4: Account for Labor and Supervision
Every loom needs an operator. Some looms also need a dedicated maintenance technician. Include both in the TCO. For the operator, use the wage cost plus statutory contributions. For maintenance, allocate a portion of a full-time technician to the number of looms in the line. If one technician covers five looms, charge each loom one-fifth of the technician cost.
If your plant uses a shared technician, the allocation method still holds. The reason for this step is that labor is a fixed cost that does not scale with output the same way energy does. A low-volume loom still needs a person to load yarn, monitor the weave, and clear jams. Ignoring labor makes the machine look cheaper than it is.
Step 5: Price Downtime and Lost Production
Downtime is the cost of not weaving. Calculate the value of one hour of lost production. Take the fabric value per hour, subtract variable costs such as yarn and energy, and you have the contribution margin per hour. Multiply that by the expected downtime hours per year.
Expected downtime comes from two sources. Planned downtime for maintenance is already in Step 3. Unplanned downtime is harder to estimate. Use your plant’s historical availability rate. If a similar loom line runs at 88 percent availability over a year, the remaining 12 percent is downtime. Convert that into hours and apply the contribution margin.
The reason for this step is that downtime is often the most painful cost. A machine that breaks down twice a week may look affordable in parts and labor, but the lost fabric value adds up quickly. Including downtime forces you to weigh reliability against purchase price.
Step 6: Include Disposal and Resale
At the end of the useful life, the loom has some value. It may be sold, traded in, or scrapped. A used loom in good condition can fetch a fraction of the original price. A loom that has been heavily modified or is near the end of its life may fetch little or nothing.
Estimate a residual value at the end of the expected life. Subtract that from the sum of all previous costs. If the machine has no resale value, the disposal cost is just the scrap fee. If it has value, the net cost is lower. Do not assume a high resale value just to make the numbers look better. Use a conservative figure and flag it.
The reason for this step is that disposal affects the total cost by a smaller amount than energy or maintenance, but it matters when comparing machines with different expected lives. A machine that holds value better at the end of its life reduces the net TCO.
Step 7: Apply the Discount Rate
If you are comparing a machine with a ten-year life against one with a fifteen-year life, the timing of costs matters. A cost incurred in year one is more expensive in today’s money than a cost incurred in year ten. Apply a discount rate to each annual cost to bring it to present value.
The discount rate should reflect your cost of capital or the return you could earn on that money elsewhere. A lower rate means future costs are less penalized. A higher rate means future costs are heavily discounted. Use the same rate for every machine you compare. The reason for this step is that raw sums of future costs overstate the present burden. Discounting gives a fairer comparison.
Step 8: Sum and Verify
Add the present values of all cost categories. Purchase, installation, energy, maintenance, labor, downtime, and disposal. The result is the loom TCO calculation for the expected life.
Before you finalize the number, verify it. Walk through the spreadsheet in reverse. Start from the final sum and trace each line back to its source. Check that every part is included in the maintenance list. Check that the energy calculation uses the correct tariff. Check that the downtime rate matches your availability data. A single missing line item can skew the total by a large margin.
Common Mistakes in Loom TCO Calculation
The most frequent error is using peak power instead of average power for energy. This inflates the energy cost and can make a machine look unattractive when it is actually efficient.
Another mistake is ignoring the labor allocation. If one technician covers six looms, each loom bears a share of that cost. Skipping it hides the true operating expense.
A third error is assuming zero downtime. Every machine loses production time. If you do not include it, the TCO understates the real cost.
A fourth mistake is using a too-short useful life. A loom that actually runs for fifteen years but is modeled for ten will have a higher annual cost in the model. Align the life with your actual replacement plan.
A final mistake is mixing currencies or exchange rates when comparing imported and domestic machines. Convert all costs to the same currency at the same exchange rate, and note the date.
Final Verification Step
Run the calculation twice. Use the same inputs and the same discount rate. If the two results match, the model is internally consistent. If they differ, find the discrepancy.
Then present the result with a table. List each cost category, the annual amount, the present value over the life, and the total. Share the table with the finance team and the plant manager. Ask them to challenge each line. The people who operate the looms often know where the model is wrong. Their input improves accuracy.
Finally, use the verified TCO to make the decision. Compare the total cost against your budget and against alternative machines. The loom with the lowest TCO is not always the best choice if it has other drawbacks, but it is the most defensible starting point for a capital planning review.
Cost Comparison Table
| Cost Category | Typical Input | Present Value Basis |
|---|---|---|
| Purchase and installation | Supplier quote plus site work | Year zero |
| Energy | Average kW times hours times tariff | Annual, discounted |
| Maintenance | Parts plus labor per interval | Annual, discounted |
| Labor | Operator plus technician share | Annual, discounted |
| Downtime | Lost contribution margin per hour | Annual, discounted |
| Disposal | Resale or scrap value | End of life, discounted |
Frequently asked questions
How often should I update the loom TCO calculation?
Review it annually and again before any major replacement decision. Energy tariffs, labor rates, and part prices change, and those updates shift the total.
Can I use a rough estimate if I do not have exact supplier data?
Yes. Use a range and label each assumption clearly. A conservative estimate that is transparent is more useful than a precise number that is wrong.
Should I include the cost of the building or foundation in the TCO?
Only if the foundation or bay is built specifically for this machine. If the structure already exists, do not allocate its cost to the loom.
How do I handle a machine that will be sold before the end of its useful life?
Model the expected sale year and apply a realistic resale value at that point. Do not assume the machine will run to the end of its design life if your plan is different.
Is the discount rate the same as my loan interest rate?
Not necessarily. The discount rate reflects your opportunity cost of capital. If you finance the purchase, the loan rate is one input, but your true cost of capital may differ.